


South Florida Buyer Guide · 2026Is Now a Good Time to Buy a Home in South Florida—or Should You Wait?The honest answer depends less on headlines and more on your monthly payment,

Dated: September 16 2026
Views: 46
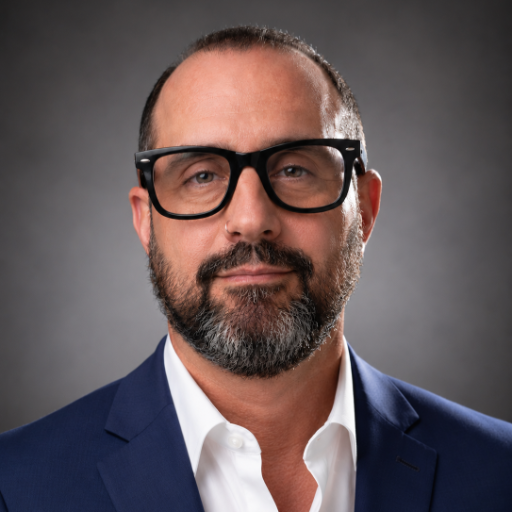
I’m Kristian Alvarez, a bilingual Realtor® with Canvas Real Estate serving buyers, sellers, and real estate investors throughout Miami-Dade and Broward County.I help first-time homebuyers, r....
South Florida Buyer Guide · 2026Is Now a Good Time to Buy a Home in South Florida—or Should You Wait?The honest answer depends less on headlines and more on your monthly payment,
Miami Relocation UpdateIf Florida’s New Property-Tax Break Passes, Moving Before December 31 Could Pay OffEstablishing permanent Florida residency before the end of 2026 could determine how
Dahiana RojasRealtor® · Canvas Real EstateENGLISH | ESPAÑOLFlexible Living Listing · West Little River, Miami2281 NW 81st TerraceMiami, FL 33147 · West Little River
Dahiana RojasRealtor® · Canvas Real EstateENGLISH | ESPAÑOLWaterfront Listing · Plantation Key, FL125 Gardenia StreetPlantation Key, FL 33070 · Plantation Key Colony,
Should you require assistance in navigating our website or searching for real estate, please contact our offices at 786-237-0797.

 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 25, 2026 7:16 PM UTC The listing information on this page last changed on Last updated on September 25, 2026 7:16 PM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 25, 2026 7:16 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
 Copyright Southeast Florida Multiple Listing Service © 2026. Accuracy of listing information is not guaranteed. Listing information is provided for personal consumer, non-commercial use, solely to identify potential properties for potential purchase. All other use is strictly prohibited, is a violation of the terms of use, and may violate federal and state law.
Data Last Updated: September 25, 2026 7:26 PM UTC
 © 2026 Florida Gulf Coast MLS (FGCMLS) Information deemed reliable, but not guaranteed. The IDX data relating to real estate for sale on this web site comes in part from the Florida Gulf Coast Multiple Listing Service. The information being provided is for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed.
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Doral may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 7:07 PM UTC
Show More...
